Latest from BCA Research
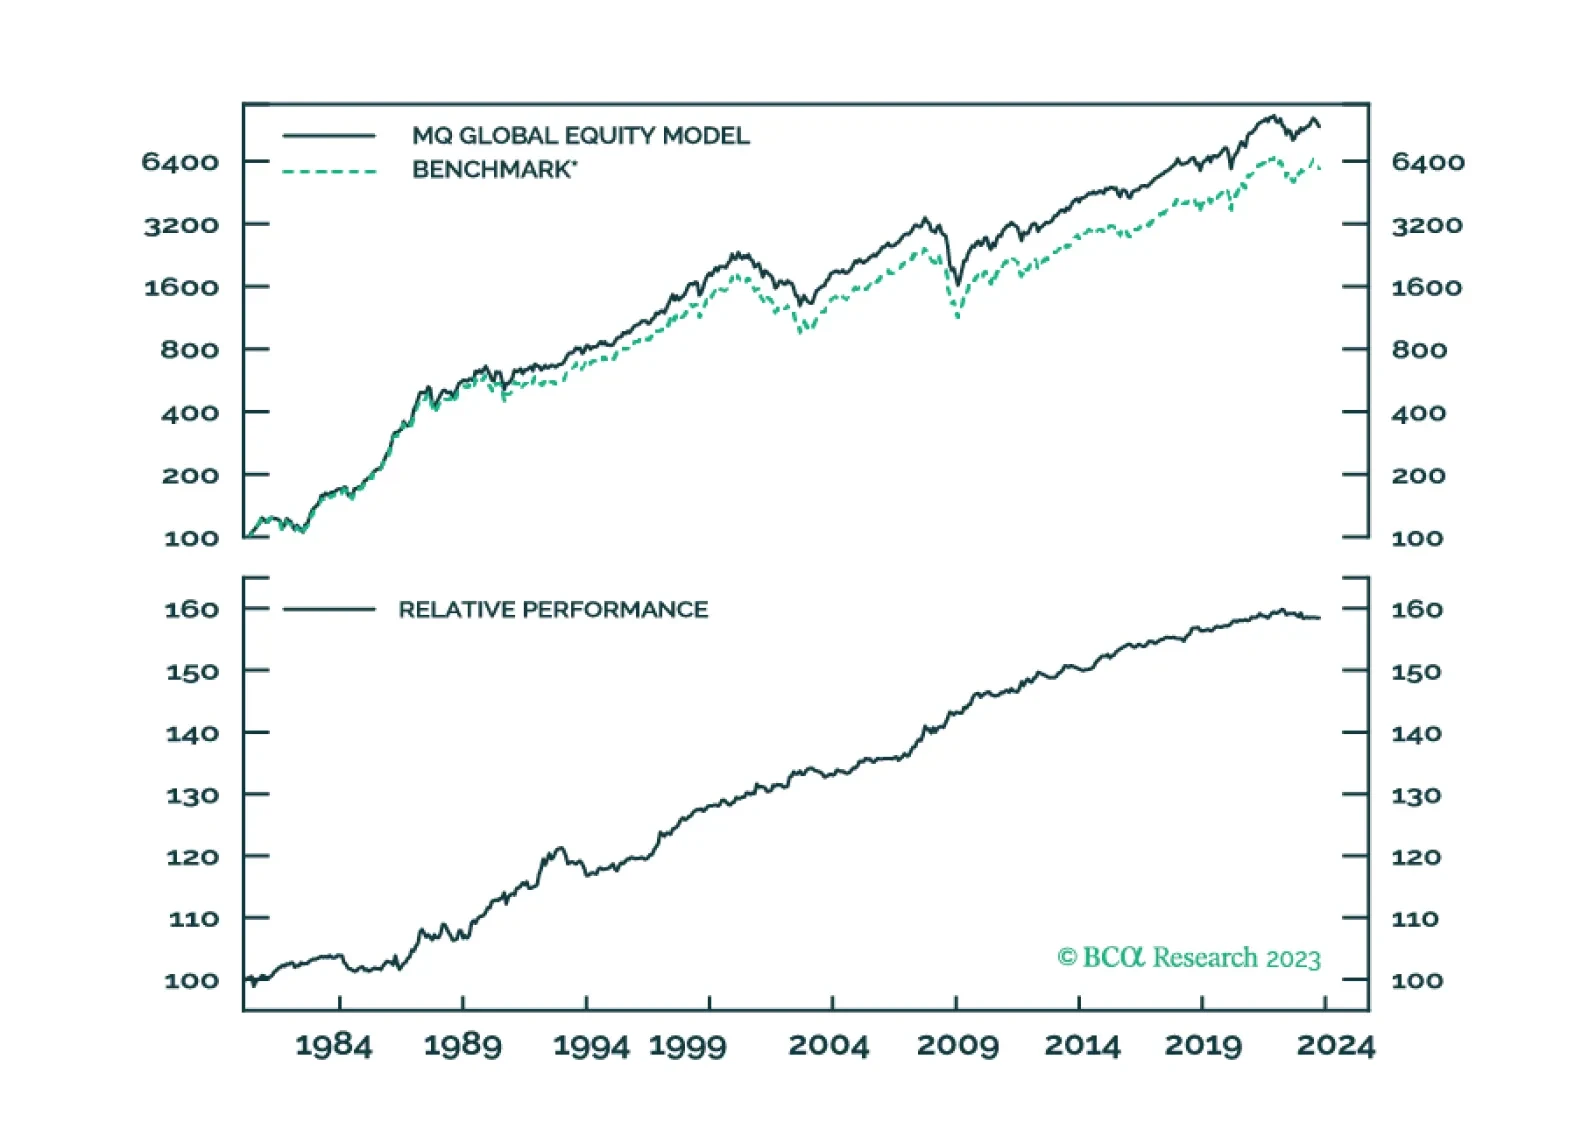
MacroQuant is holding a near neutral positioning with a slight tilt towards equities and bonds and away from cash.
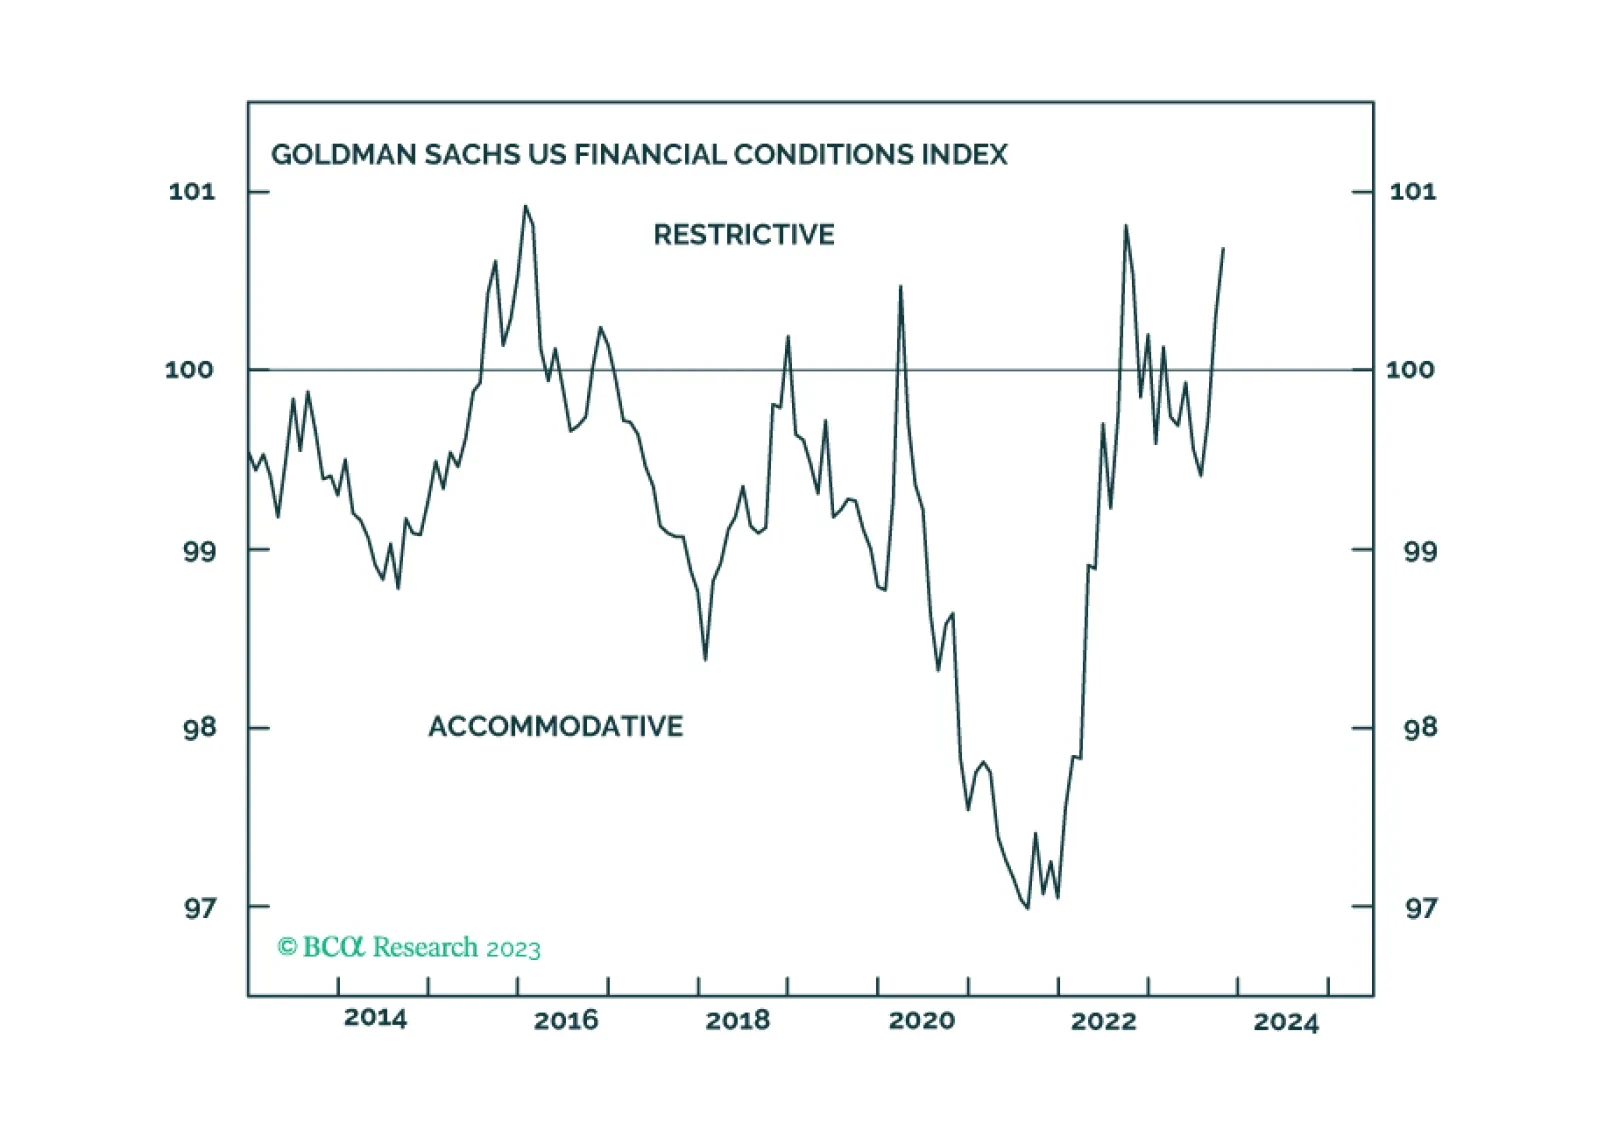
Our reaction to today’s FOMC meeting and the Treasury’s Quarterly Refunding Announcement.

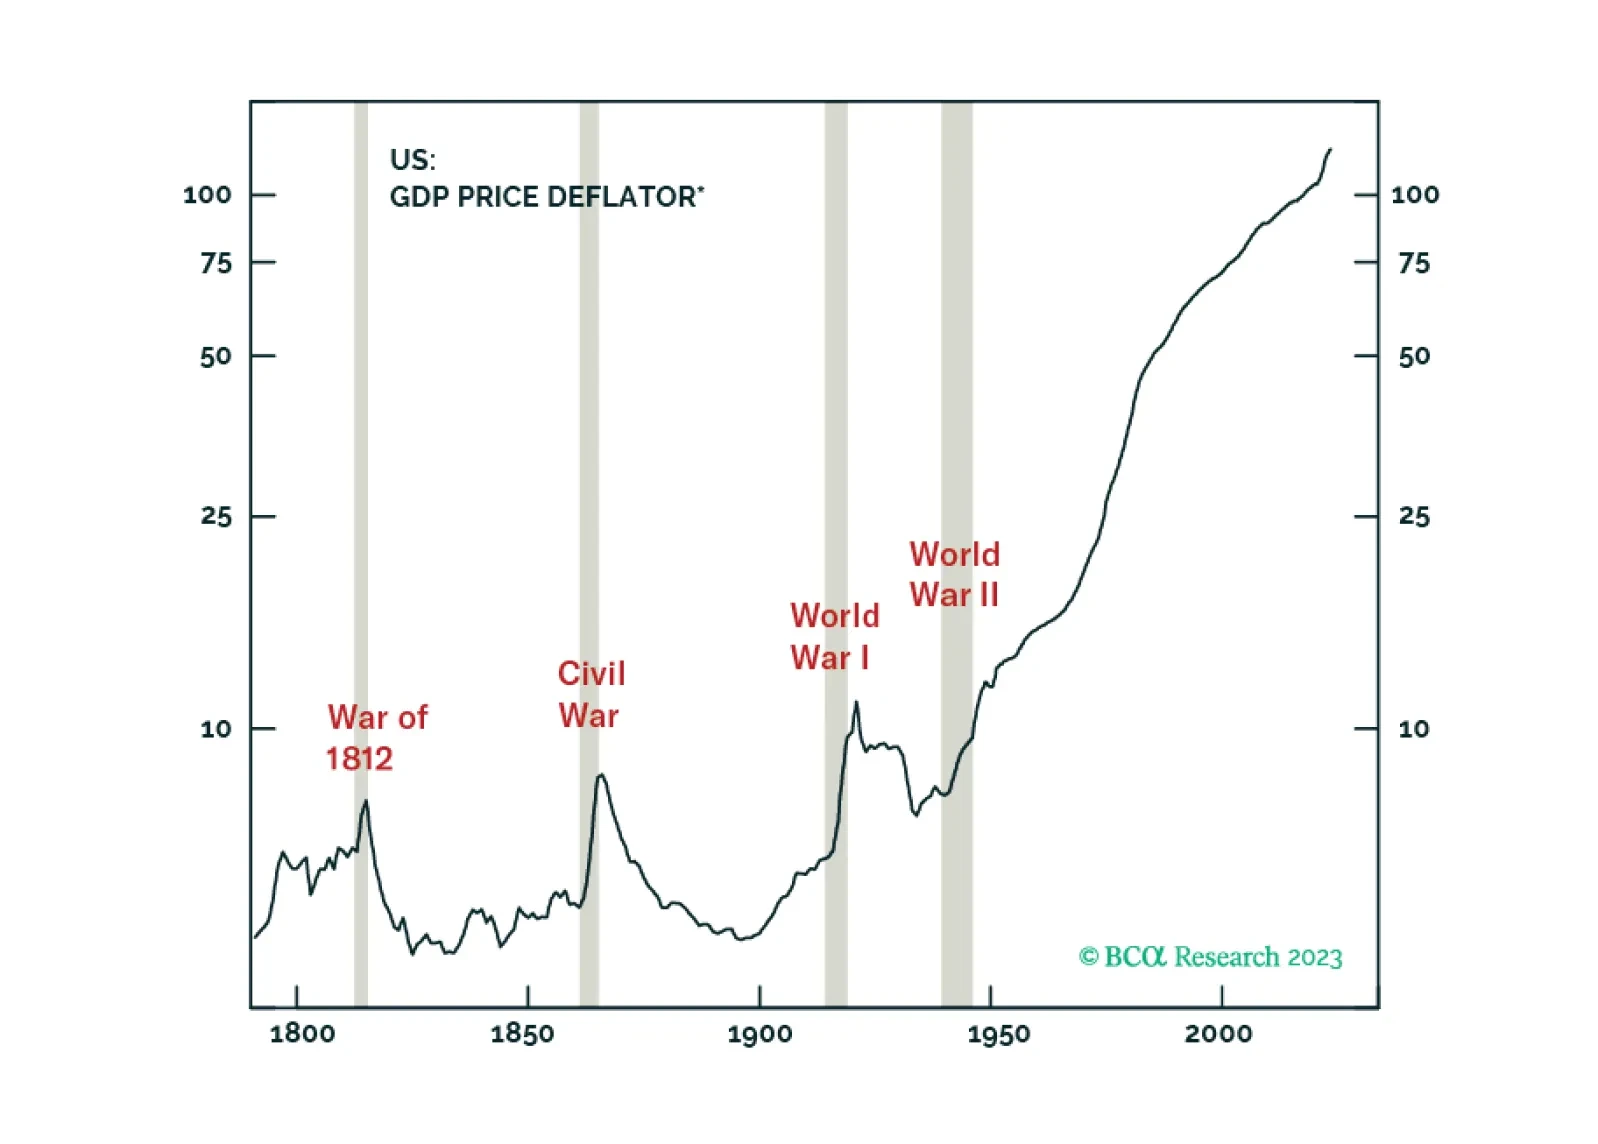
The fundamental component of long-term inflation expectations has climbed to its highest level since 2008 in both the US and the euro area. This means that both the Fed and the ECB will need to engineer inflation to undershoot 2 percent for an extended period if they are to maintain their 2 percent inflation targets. We explain what this means for investment strategy over the coming 6-12 months. Plus, we pinpoint what to focus on in this Friday’s US jobs report. And we identify food and beverages (PBJ) and the Indonesian rupiah (IDR/USD) as excellent rebound candidates.

We maintain our view that China’s economic growth in the coming months will remain lackluster. Beijing's recent measures to provide additional financing may help to bridge the gap in government spending in the rest of 2023 and into 2024, but the impact on growth will be very limited.

High interest rates will eventually cause growth to slow. Signs of stress are already starting to show. Stay cautiously positioned.

What will the next manufacturing cycle look like in Europe and how will risk assets perform? Lessons from the recent past.

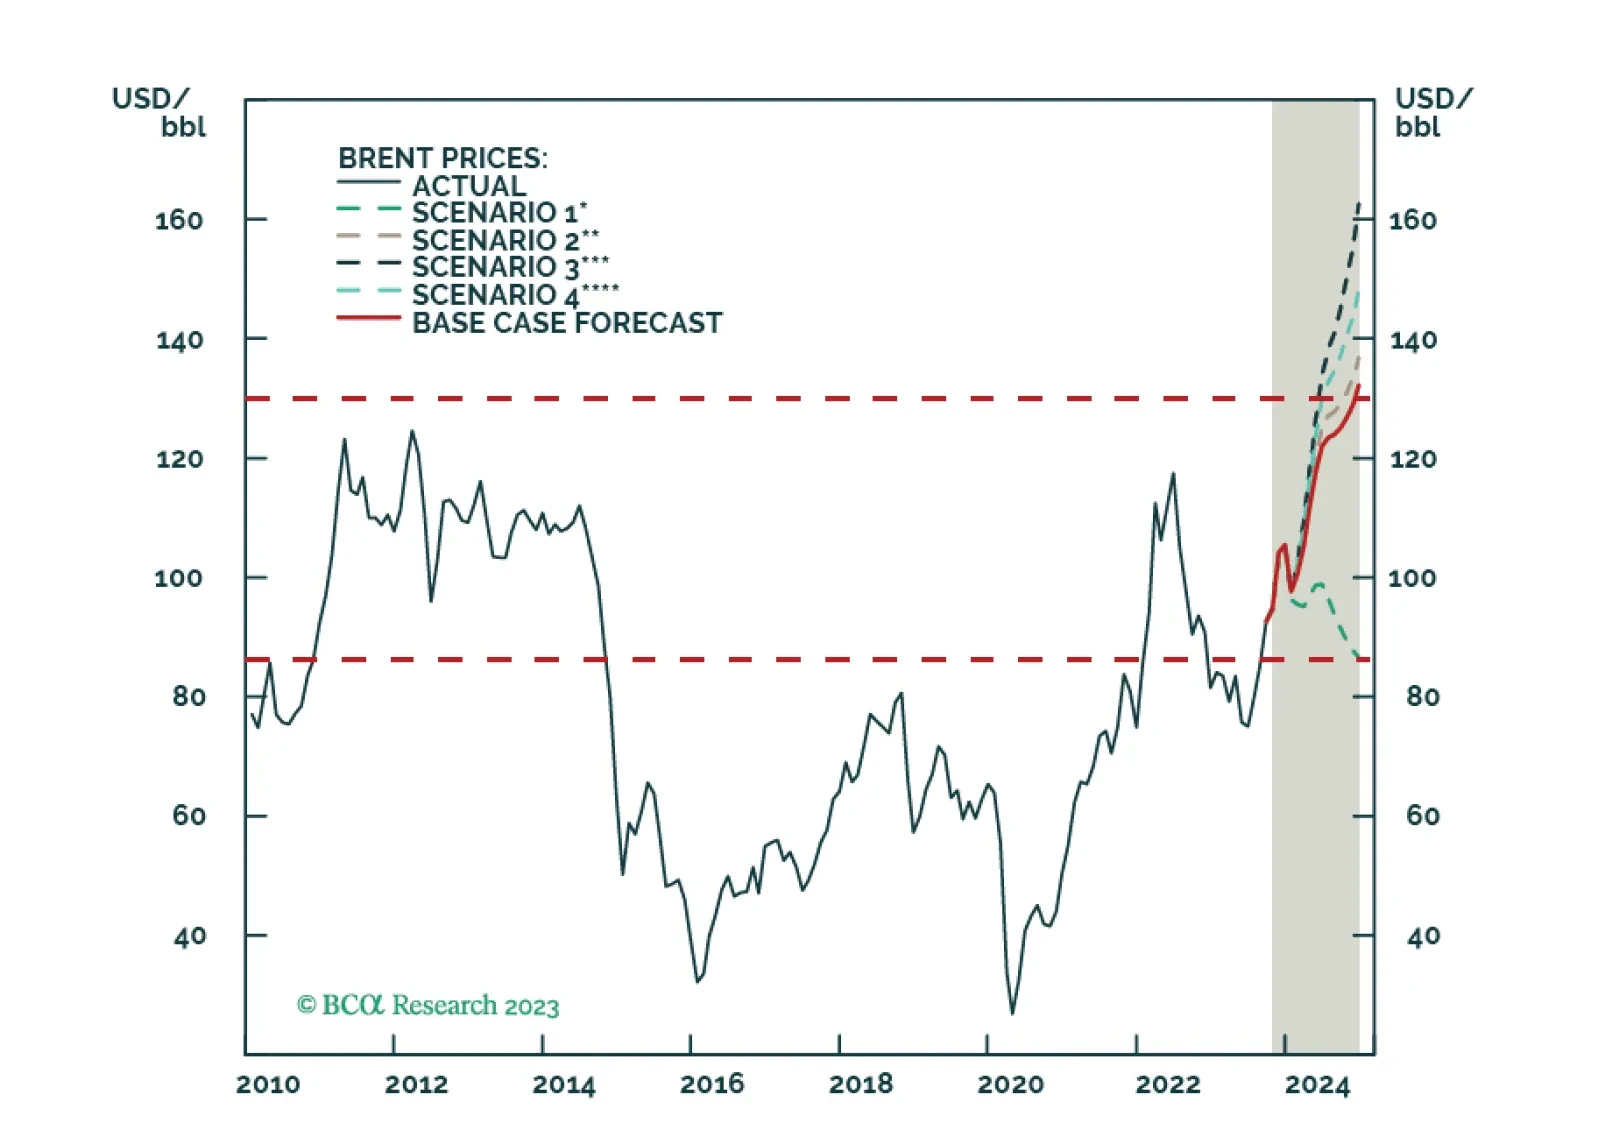
Stronger US growth elicits a response from the House Republicans. But a government shutdown is not devastating to the economy. What is more devastating would be a crisis in the Middle East, Europe, and Asia. Stay long US defense, energy, and large caps stocks.

A look at recent data on economic growth, inflation and the labor market, and a discussion of the implications for Fed policy and bond strategy.